background graphical layerbackground graphical layerbackground graphical layerbackground graphical layer

Restaurant Insurance in California

Operating in hospitality means juggling guests, staff, and reputation, often all at once. Our Hospitality & Restaurants coverage plans help you manage the risks that can interrupt service or damage your bottom line.

Contact Us
  • California Corporate Insurance License #0I5358
  • 40+ years of combined team experience
  • 4.9/5 star rated for service excellence
  • 500+ insured companies
Call 866-856-3846

Restaurant insurance in California typically combines general liability for customer injuries, commercial property for the building contents and kitchen equipment, spoilage and business interruption coverage, workers’ compensation for staff and, where alcohol is served, liquor liability. Homewell, an independent broker, compares carriers that write hospitality risks.

Updated

Get My Free Quote

What insurance does a restaurant need?

Restaurants commonly need general liability for customer incidents, property coverage for equipment and contents, workers’ compensation for staff, commercial auto for delivery vehicles and business interruption for lost income. Those serving alcohol should add liquor liability, and many add cyber coverage because they take card payments.

  • General liability for customer incidents
  • Property coverage for equipment and contents
  • Workers’ compensation for staff
  • Liquor liability when alcohol is served
  • Business interruption and spoilage coverage

Your lease and local rules may also specify what you must carry.

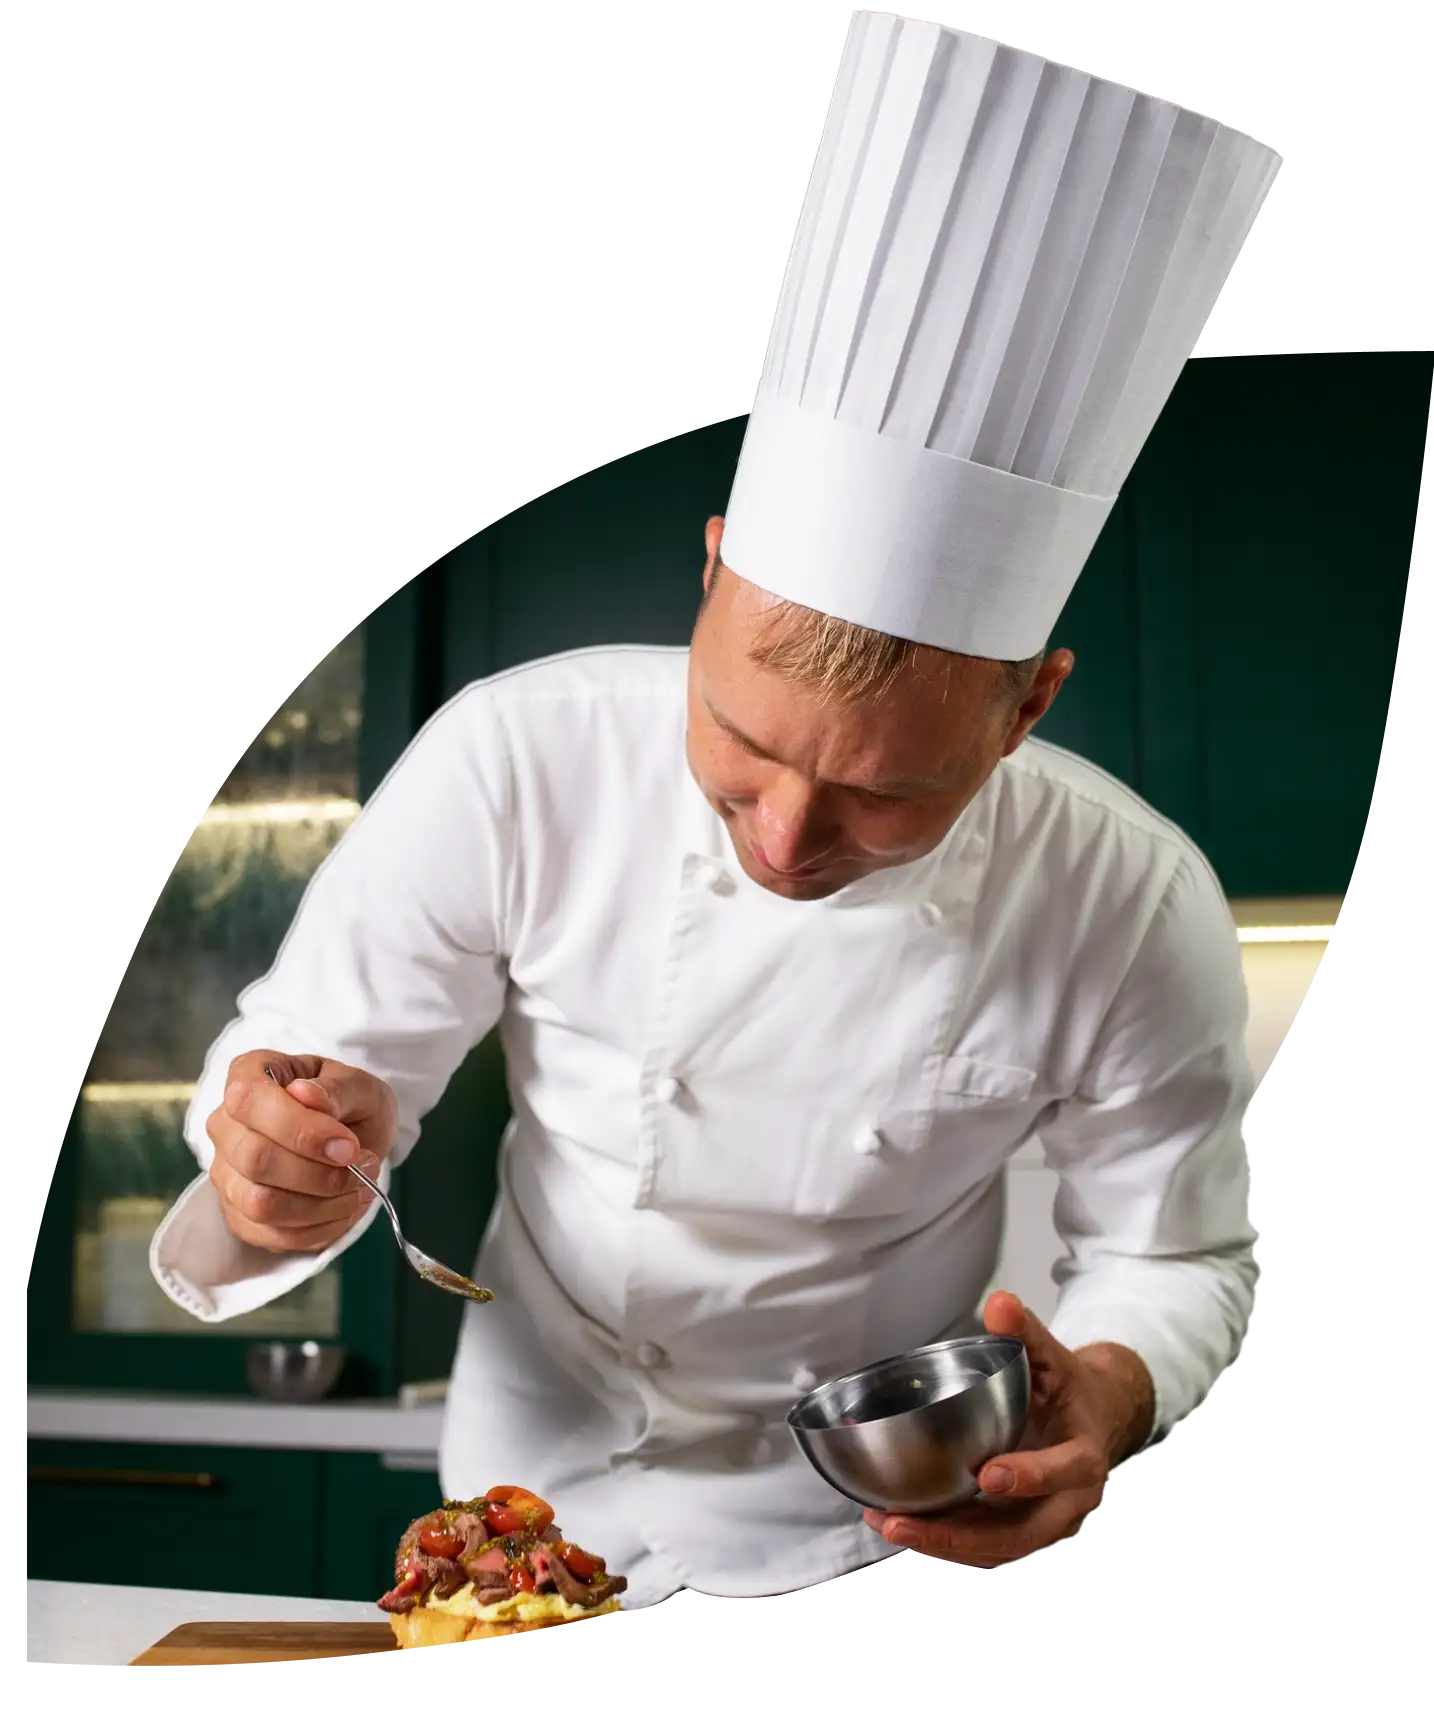
Deliver an Exceptional Experience. We build programs specifically for restaurants, bars, cafes, hotels, and event venues. Whether you need commercial property insurance for a storefront, liquor liability insurance for a bar, or business interruption insurance for restaurants to cover lost revenue while you rebuild, we tailor solutions to fit the size and risk profile of your business.

a masterful chef working on a dish

Does restaurant insurance cover food-borne illness?

Claims that a customer became ill from food you served are generally handled under the products portion of general liability, subject to the policy’s terms and exclusions. Some policies add coverage for business income lost during a health-related closure. Review the wording, since coverage for illness claims varies.

Food safety training and records help prevent claims and support your insurance position.

Do I need liquor liability insurance?

If you serve or sell alcohol, you should consider it. General liability policies typically exclude liquor liability, which covers claims that alcohol you served contributed to injury or damage. Contracts, landlords and local requirements may also call for it, so confirm what applies to your restaurant.

Staff training and responsible service practices matter to both safety and underwriting.

What happens if a power outage spoils my food?

Spoilage coverage can reimburse food loss caused by equipment breakdown or a power outage, depending on the policy’s causes of loss and conditions. Many policies limit it, so ask what events are included. Business interruption coverage may also help if the restaurant has to close after a covered loss.

Keep a record of inventory and temperatures to support any claim.

How do I get restaurant insurance quotes in California?

Tell Homewell about your restaurant, menu, seating, alcohol service and staff. An independent broker compares carriers that write hospitality, explains the options in plain language and returns tailored quotes. Requesting a quote is free, and you decide whether to move forward.

  • Type of restaurant and location
  • Alcohol service and entertainment
  • Delivery or catering operations
  • Equipment and inventory values
a group of peoplea group of peoplea group of peoplea group of peoplea group of people

WHY HOMEWELL?

Local Hospitality Expertise

We understand restaurant and hotel operations and design policies that reflect real-day-to-day risks, including hospitality insurance nuances.

Key takeaways

  • Restaurants combine liability, property, spoilage, business interruption and workers’ compensation.
  • General liability usually excludes liquor liability, so serving alcohol needs its own cover.
  • Spoilage coverage depends on which causes of loss are included.
  • Delivery vehicles and card payments add auto and cyber exposures.
  • An independent broker compares carriers that write hospitality.

Frequently asked questions

Do I need insurance for catering or food trucks?

Yes. Off-premises catering and mobile food operations create exposures that a restaurant policy may not cover, so tell your broker about them.

Does restaurant insurance cover delivery drivers?

It depends. Employee drivers and delivery vehicles may need commercial or hired and non-owned auto coverage, and third-party platforms have their own rules. Describe your delivery model to your broker.

What coverage helps if a customer is injured in the parking lot?

General liability can respond to injuries on premises you are responsible for, depending on your lease and the policy terms.

Is insurance required by my landlord?

Often. Leases commonly require liability and property coverage with specified wording, so check your lease and ask your broker to review it.

Keep your doors open and your reputation intact.

Call 866-856-3846 or send your email below and we’ll reach out with options.

This page is general information, not a policy or legal advice. Coverage, exclusions, licensing rules and eligibility vary by carrier, policy and operation, so confirm the specifics for your business with a licensed agent before you buy.

California Corporate Insurance License #0I5358. Ontario, CA 91764. Content last updated .